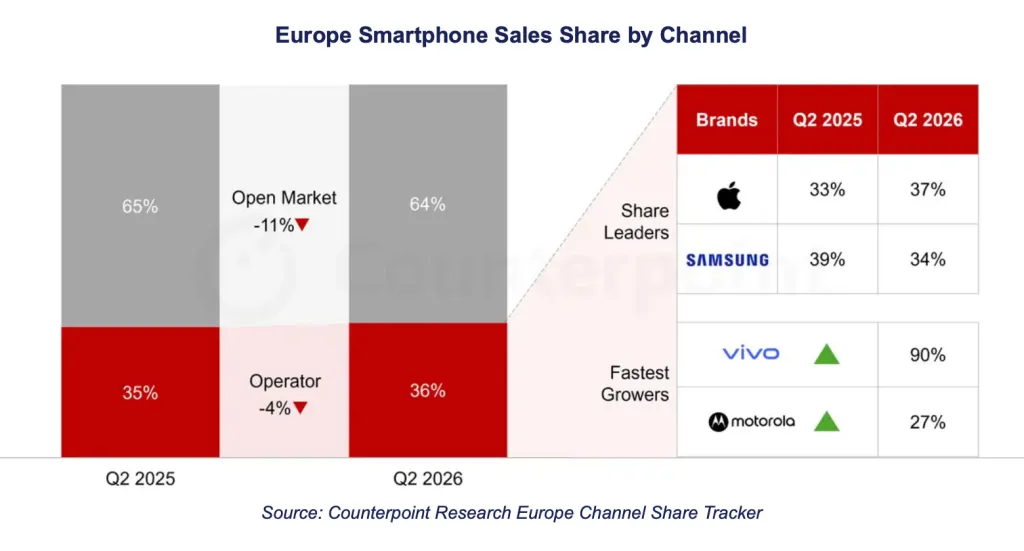
In a significant shift for the European smartphone market, Apple has claimed the top spot in operator-channel sales for the second quarter of 2026, surpassing Samsung. This comes as overall smartphone sales in Europe saw an 8% year-over-year decline, though operator channels proved more resilient with only a 4% drop compared to an 11% decrease in the open market.
Operator Channels Show Resilience
Analysts attribute the strength of operator channels to a higher proportion of contract sales and a concentration of premium device purchases. These factors, combined with robust demand for flagship models, have allowed carriers to better weather the impact of rising component costs, particularly for memory.
Apple Leads, vivo Achieves Fastest Growth
During Q2 2026, Apple captured 37% of the European operator market share, inching ahead of Samsung’s 34%. This marks a notable change in leadership, as the top position has frequently shifted between these two giants in previous periods.
On the growth front, vivo delivered the most impressive performance in the operator segment, recording a 90% year-over-year increase in sales. Motorola followed with a strong 27% growth. These figures indicate substantial shifts in consumer preferences and brand strategies within the European market.
Impact of Memory Prices and Future Outlook
The increasing cost of memory components has significantly impacted the production cost of budget smartphones, disproportionately affecting the most affordable segment and the open market. Consumers opting for contract-based device purchases through operators tend to be less price-sensitive, which has contributed to the greater stability of this sales channel.
According to Jan Stryjak, Associate Director at Counterpoint Research, operator channels are likely to continue their growth trajectory in smartphone sales in the coming quarters. He also noted that the open market is expected to recover more slowly due to the ongoing influence of component price fluctuations.
This report underscores the complex dynamics of the European smartphone landscape, where premium brands and carrier-exclusive offerings are demonstrating resilience, while the budget segment and direct-to-consumer sales face considerable headwinds.