中芯国际 (SMIC), China’s largest contract chip manufacturer, has announced robust financial results for the first three quarters and the third quarter of 2026. The company reported a significant year-on-year increase in net profit, signaling strong performance in a dynamic semiconductor market.
2026 Third Quarter and Year-to-Date Performance
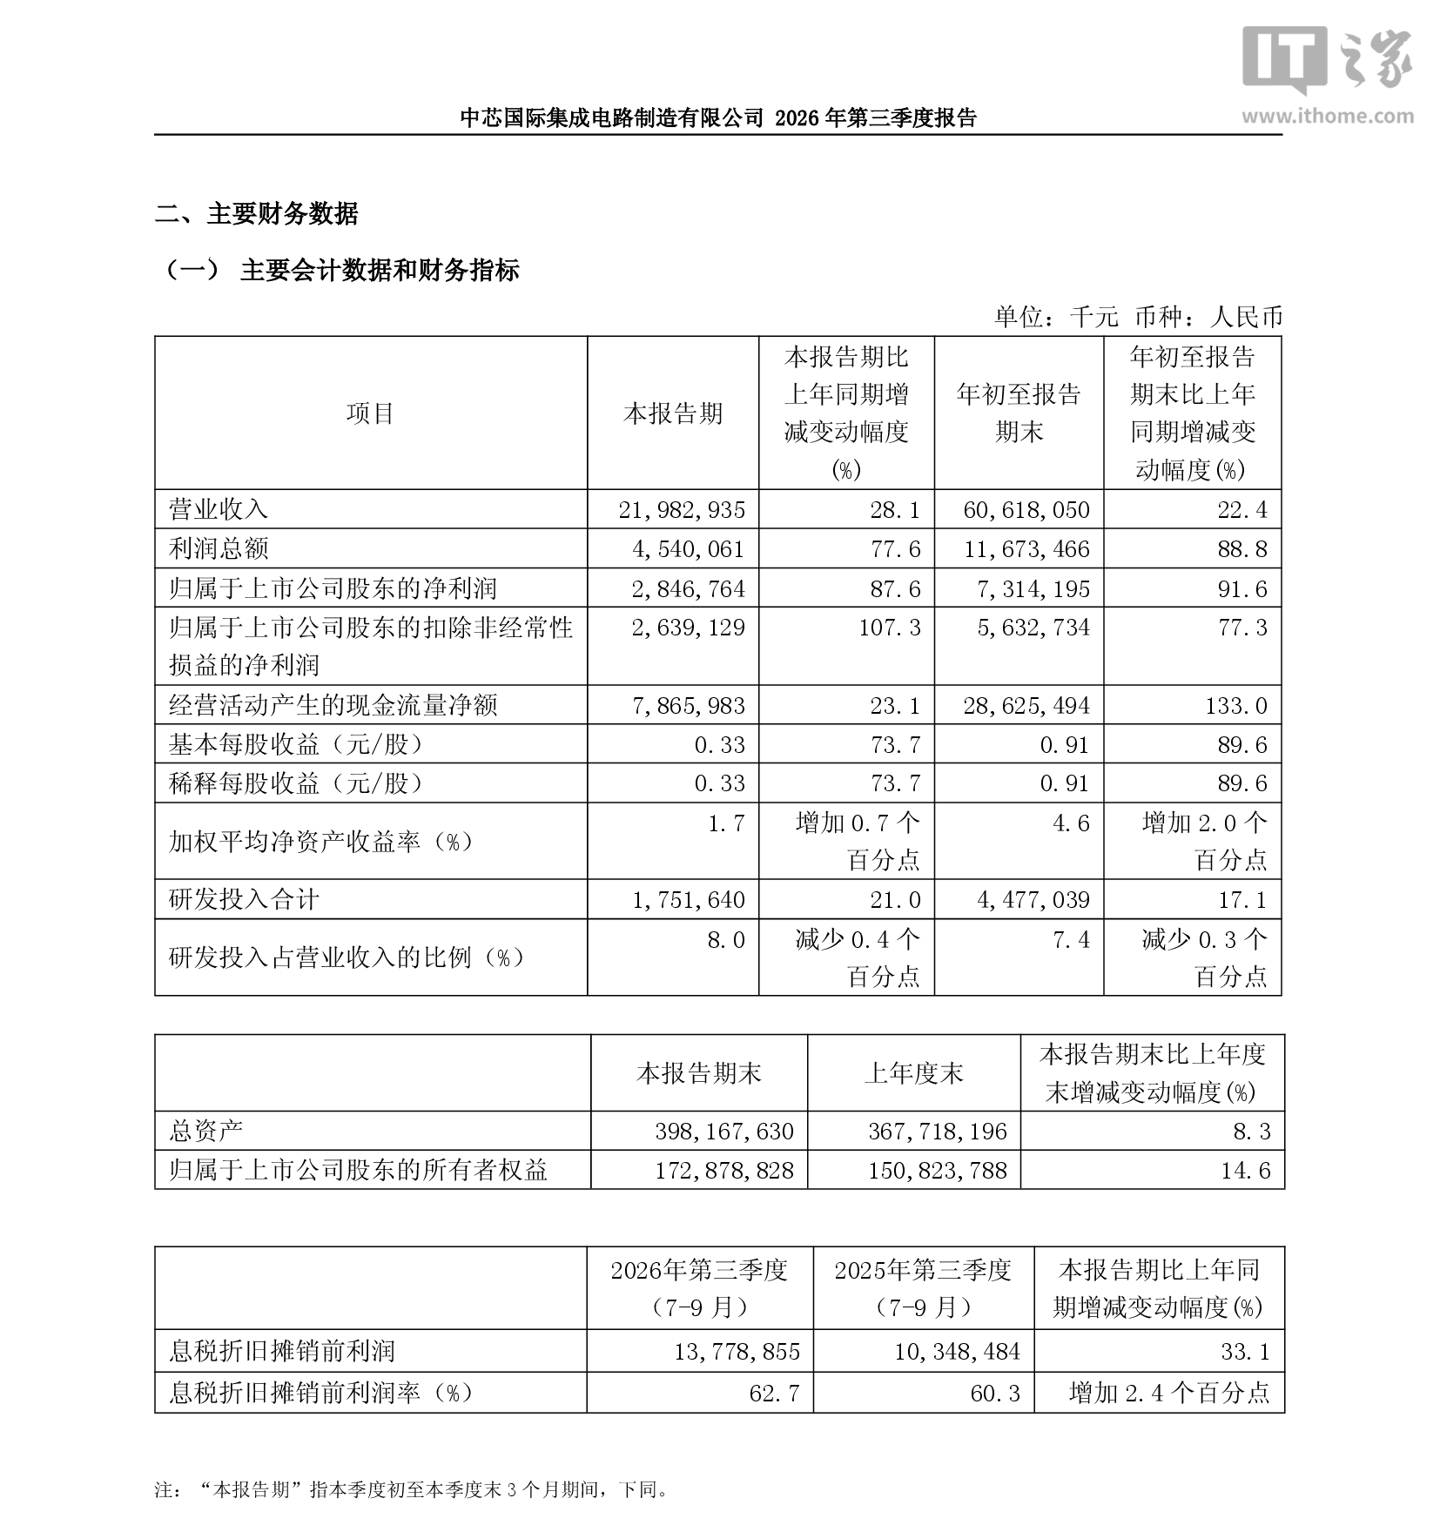
For the first three quarters of 2026 (January to September), SMIC achieved a total operating revenue of 60.618 billion yuan, marking a 22.4% increase compared to the same period last year. Net profit attributable to the parent company surged by an impressive 91.6% to 7.314 billion yuan. Operating cash flow stood at 28.625 billion yuan, with basic and diluted earnings per share both at 0.91 yuan.
The third quarter (July to September) also demonstrated strong momentum. Total operating revenue for the quarter reached 21.983 billion yuan, up 28.1% year-on-year. Net profit attributable to the parent company saw a substantial increase of 87.6%, reaching 2.847 billion yuan. Operating cash flow for the quarter was 7.866 billion yuan, and earnings per share were 0.33 yuan.
AI Interpretation and Key Highlights
The company’s performance in the third quarter exceeded market expectations. Analysts had previously predicted third-quarter sales revenue of approximately $3.09 billion and a gross profit margin guidance between 26% and 28%. SMIC’s actual sales revenue reached $3.09 billion, representing a sequential increase, and its gross profit margin climbed to 30.2%, a sequential improvement of 2.2 percentage points, significantly surpassing the market’s consensus forecast.
Year-to-Date Performance Drivers
The substantial improvement in profitability for the first three quarters is attributed to several factors: an increase in wafer sales year-on-year, a rise in capacity utilization rates, and optimization of the product mix. Non-recurring gains, particularly from investments in associated and joint ventures, also contributed significantly.
Furthermore, SMIC reported a substantial year-on-year increase of 133.0% in net cash flow from operating activities, reaching 28.625 billion yuan, indicating a significant enhancement in its sales collection capabilities.
Capacity, Operational Efficiency, and Revenue Structure
Capacity utilization rates in the third quarter reached 95.2%, a further climb from 93.7% in the second quarter, with older production lines operating at near full capacity. The company sold approximately 1.76 million wafers (equivalent to 8-inch logic wafers), a notable increase from 1.54 million wafers sold in the same period last year.
Capital expenditure followed a front-loaded, then stable rhythm. Third-quarter capital expenditure amounted to 7.174 billion yuan, a decrease from 8.813 billion yuan in the second quarter, reflecting a dynamic balance between expansion and depreciation pressures.
Shifting Revenue Composition
Regional revenue structure shows a continued increase in domestic contributions, with China accounting for 90.8% of revenue (up from 86.2% in the same period last year). The US accounted for 7.8%, and Europe and Asia combined for 1.4%.
In terms of application segments, the industrial and automotive categories grew to represent 19.3% of revenue (up from 11.9% last year). Computer and tablet applications constituted 18.3%, while consumer electronics remained the largest segment at 40.6%. The smartphone segment saw a decrease in contribution to 14.3% (down from 21.5% last year).
Regarding wafer size, 12-inch wafers continued to gain prominence, making up 78.9% of revenue, an increase from 77.0% in the previous year.
Fourth Quarter Guidance and Outlook
Looking ahead, SMIC anticipates fourth-quarter revenue to grow by 0% to 2% sequentially, with a gross profit margin guidance of 28% to 30%. The company notes that the slight sequential decline in gross margin is a normal seasonal fluctuation, considering the current high capacity utilization, the gradual release of price increase benefits, and the depreciation pressure from new capacity.
SMIC is committed to expanding capacity driven by customer demand and building a leading advantage through a high-value product mix, enhancing its operational resilience to navigate market cycles.
Investment Value Considerations
Key points for investors include the sustainability of the price increase cycle for mature process technologies, which is a critical factor for future gross margin expansion. The sustained demand for AI peripheral chips (power management, signal chain) and automotive-grade chips needs careful monitoring, alongside potential order fluctuations after consumer electronics clients potentially de-stock after ahead-of-schedule inventory buildup.
Investors are advised to focus on the trend of net profit attributable to the parent company after deducting non-recurring items, as non-recurring items like the passive dilution of associate equity and changes in fair value of financial assets can significantly impact profits.
This report is based on AI analysis and does not represent the views of IT之家. Please refer to official disclosures for the most accurate information. This content does not constitute investment advice.